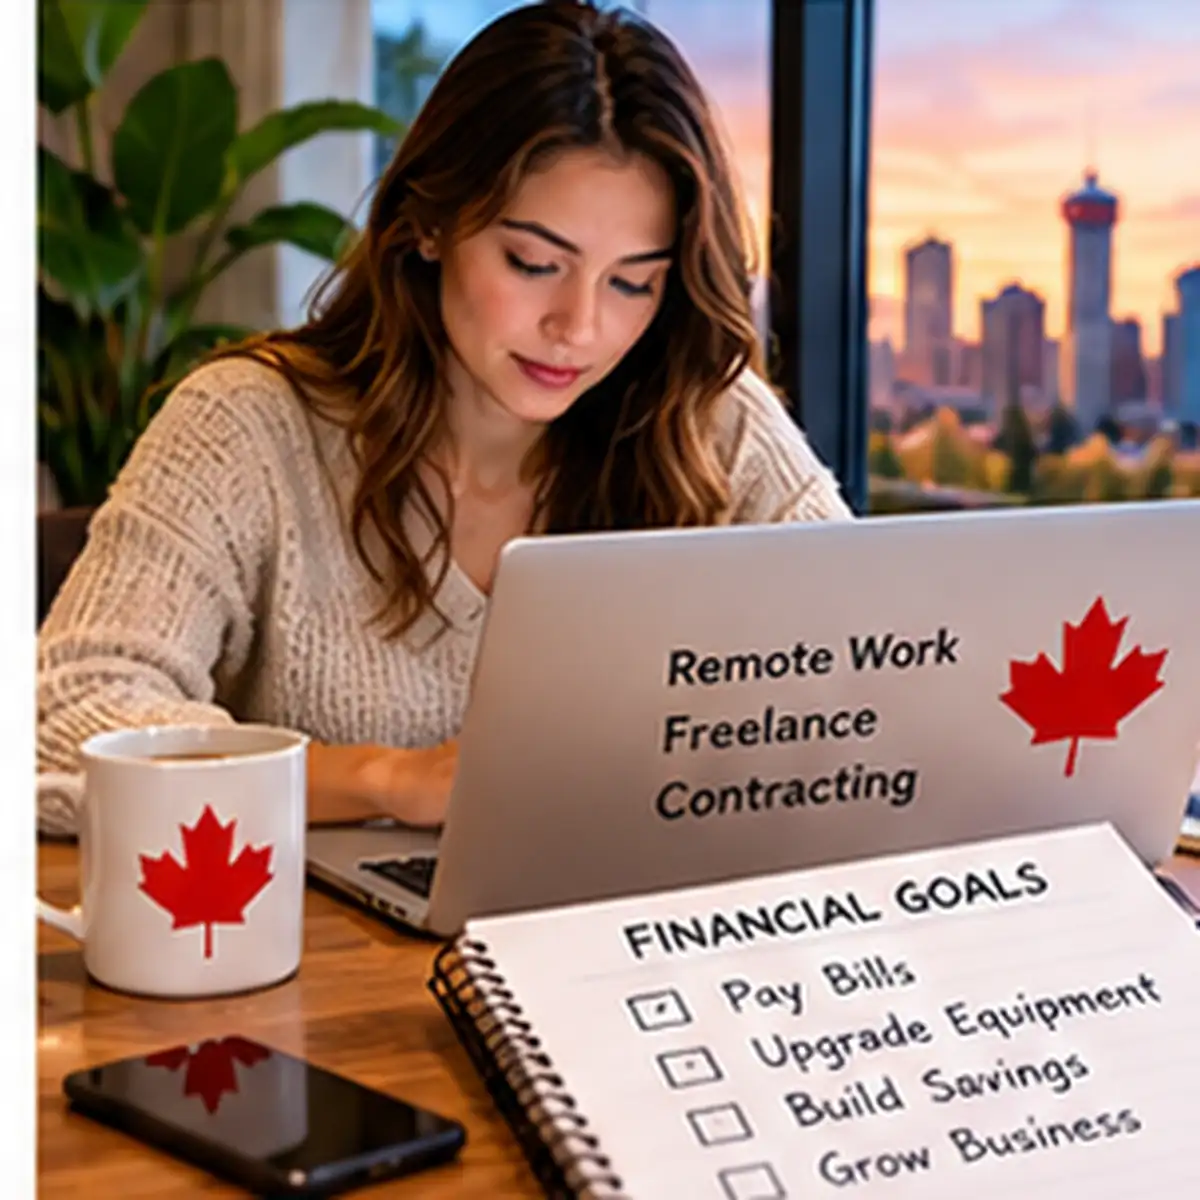
 Remote employment has changed the way many Canadians earn a living. Professionals can now work from home, smaller communities, or shared office spaces while receiving income from employers located elsewhere. Although remote work can provide flexibility, it also raises questions about employment verification and financial documentation. Canadians exploring trusted Alberta lending services may want to understand how lenders evaluate remote employment, what information applicants should prepare, and how to determine whether financing is affordable.
How Remote Employment Differs From Traditional Office Work
Remote work allows employees to perform their responsibilities away from a conventional workplace.
Some work exclusively from home, while others divide their schedules between remote and office locations.
A remote employee may live in Alberta while working for a company headquartered in Ontario or another jurisdiction.
This arrangement does not necessarily change the person’s status as an employee.
However, it can affect how employment information is presented during a loan application.
Applicants should clearly identify their employer, employment status, and income source.
Employment Verification for Remote Workers
Lenders commonly request information to verify employment and assess income.
Depending on the product, applicants may need to provide recent pay statements, bank deposit records, or an employment letter.
Some lenders may contact employers to verify information according to their policies.
Remote work itself does not automatically make someone ineligible for financing.
The lender is generally more concerned with whether income is verifiable and sufficient for the proposed repayment obligation.
Applicants should provide accurate information and be prepared to explain unusual payroll arrangements if necessary.
Employees Versus Independent Contractors
One important distinction is whether the remote worker is employed by a company or operates independently.
A salaried remote employee may receive regular payroll deposits and conventional employment documents.
An independent contractor may invoice clients and receive payments at irregular intervals.
Lenders may assess these situations differently.
Contractors might be asked to provide additional financial documentation, such as tax information or business banking records.
Understanding employment classification helps applicants prepare the appropriate records.
Working for an International Employer
Some Canadians work remotely for companies based outside Canada.
Payment arrangements may involve foreign currencies, international transfers, or payroll providers.
These arrangements can complicate income verification.
A lender may require evidence showing the Canadian-dollar value of income received and whether earnings are consistent.
Exchange-rate fluctuations can also affect the amount available for household expenses.
Applicants should avoid overstating income by relying on unusually favourable exchange rates.
Using realistic income estimates is important when assessing borrowing affordability.
The Financial Benefits and Costs of Remote Work
Remote employees may save money on commuting, parking, and certain workplace expenses.
However, working from home can introduce other costs.
Internet service, office equipment, electricity, furniture, and technology upgrades may become part of the household budget.
Some expenses may be reimbursed by an employer, depending on company policies.
Workers should understand which costs they are personally responsible for before considering borrowing to purchase equipment.
Financing Essential Work Equipment
A damaged computer or malfunctioning internet equipment can interfere with remote employment.
Before obtaining credit to replace essential equipment, ask whether the employer provides replacement devices or reimbursement.
Some companies maintain policies for approved technology expenses.
If equipment must be purchased personally, compare repair options, refurbished products, and available financing arrangements.
A loan should be evaluated according to total cost and repayment affordability.
Protecting Personal Information During Applications
Remote workers are accustomed to completing tasks digitally, but this familiarity should not replace careful security practices.
Verify the lender before submitting identification or banking details.
Use secure connections and avoid suspicious messages promising automatic approval.
Review privacy policies and the full agreement.
Keep electronic copies of documents and payment schedules in a secure location.
Making Responsible Borrowing Decisions
Remote employment can provide flexibility, but household financial obligations remain the same.
Before borrowing, calculate available income after essential expenses.
Consider the stability of employment, any outstanding debts, and potential changes in working arrangements.
A well-planned borrowing decision depends on verifiable income and manageable repayment terms rather than the location where the applicant performs their work.
For Canadian remote workers, good financial records and realistic budgeting can make borrowing decisions easier to evaluate.